
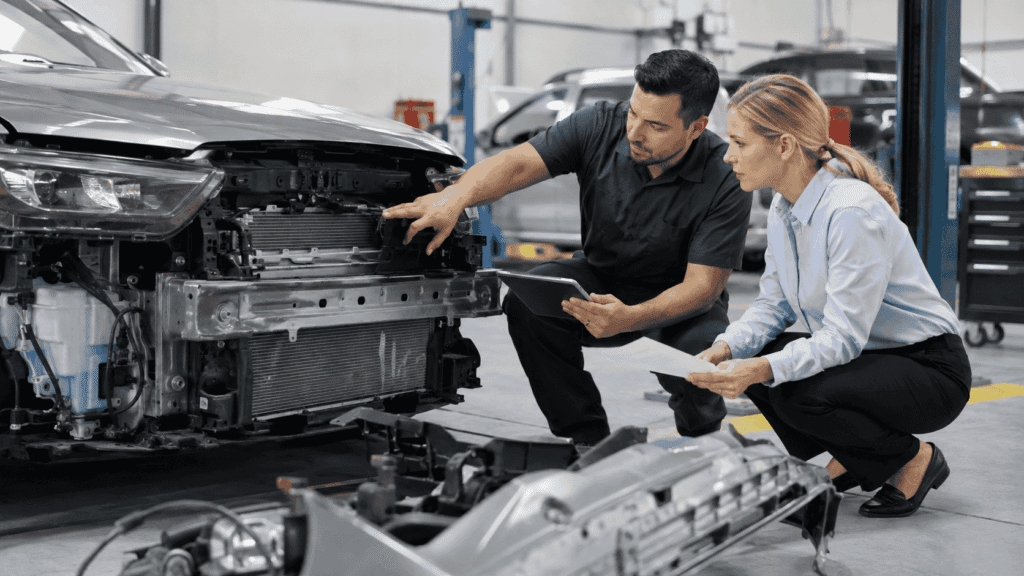
If insurance totals your car after repairs start, the insurer usually reopens the math after new damage or higher repair costs appear. The claim may shift from a repair path to a total loss review if the revised repair cost gets too close to, or exceeds, the vehicle’s value under the policy and state rules.
That does not mean the shop did anything wrong or that every supplement leads to a total loss. It often means the first estimate was based on visible damage, then teardown revealed parts, sensors, structure, labor, or procedures that were not clear at the start.
Quick Summary
- An initial estimate can change after teardown reveals hidden damage.
- The shop may submit a supplement for added repair cost.
- The insurer may compare the revised repair cost with actual cash value.
- A total loss review can happen even after repair work has started.
- Ask what work was completed, what is pending, and how the settlement will handle charges.
Why Insurance May Total Your Car After Repairs Start
Early estimates are often preliminary. A photo estimate or exterior inspection may catch the obvious damage but miss what is behind a bumper cover, grille, lamp, wheel liner, door skin, or quarter panel. Once the shop removes parts, it may find damaged brackets, wiring, cooling components, sensors, frame measurements, calibration needs, or other damage from the same loss.
The Maine Bureau of Insurance explains, as a state example, that additional damage can be discovered once repairs have begun and the shop may submit an additional estimate to the insurer for approval.
If the revised numbers change the economics, the file may move toward CPA’s broader guide to total loss in car insurance.
The Usual Sequence
The sequence often looks like this: initial estimate, repair authorization, teardown, hidden damage, supplement, insurer review, revised repair total, and then a decision about whether repair still makes sense.
A supplemental repair estimate is the document that captures newly discovered or newly documented repair work. It may include added parts, labor, scans, calibrations, refinishing, measurements, or price changes tied to the same loss.
The insurer can approve the supplement, approve part of it, ask for photos, reinspect the vehicle, question whether an item is related, or decide the total repair cost now requires a total loss review. A supplement is a request for review, not an automatic approval.
How the Insurer Reviews the New Math
The insurer compares the covered repair cost with the vehicle’s actual cash value and any state-specific total loss rules. The California Department of Insurance explains, as a California example, that under a standard auto policy a physical damage claim generally pays the lesser of the amount necessary to repair the vehicle or the vehicle’s actual cash value.
That concept explains why the decision can change. If the first estimate was $4,800 on a car worth much more, repair may have looked reasonable. If teardown raises the covered repair cost to $10,500 and the vehicle’s value is close to that amount, the insurer may review whether continuing repairs makes economic sense.
This overlaps with the common problem of a repair shop estimate being higher than the insurance estimate, but the key difference is timing. Here, work has already started and new information may change the claim track.
What Happens to Work Already Done?
Ask for a written breakdown. Some labor, teardown, storage, parts, diagnostics, or administrative charges may already exist. If the vehicle is sitting at a shop or tow yard, see who pays storage fees after a car accident and why timing, authorization, fault, and claim handling can affect the answer. How those charges are handled can depend on policy language, insurer approval, shop authorization, state rules, and whether the work was necessary to inspect covered damage.
Do not assume you personally owe every charge because the car became a total loss. Also do not assume the insurer must approve every line simply because the vehicle was taken apart. The facts and authorization history matter.
What to Ask Before You Agree
- What hidden damage changed the estimate?
- Which supplement lines were approved, questioned, or denied?
- What work has already been completed?
- What charges are tied to teardown, storage, diagnostics, or parts?
- What valuation is being used if the vehicle is now a total loss?
If the claim shifts to total loss, ask for the valuation report or equivalent support. The Washington Office of the Insurance Commissioner tells Washington consumers they can ask for a total loss valuation report showing the data used to decide value. Other states may use different rules.
If the value seems wrong, CPA’s guide to how to dispute an insurance claim decision is the next logical step.
Simple Example
A shop starts with a $5,200 front-end estimate. After teardown, it finds damaged cooling components, sensor brackets, and structural measurements that raise the repair to $9,400. The insurer reviews the supplement and compares the updated repair cost with the vehicle’s value. If the updated numbers meet the applicable total loss criteria, the file may change from repair to settlement.
Conclusion
Insurance may total your car after repairs start when hidden damage or added repair requirements change the economics of the claim. The realistic path is initial estimate, teardown, supplement, insurer review, and possible total loss evaluation.
Ask for the supplement, approval status, completed-work charges, and valuation support before agreeing to the next step. The cleaner the documentation, the easier it is to understand whether the decision is about repair cost, vehicle value, coverage, or state rules.
Related
FAQ
Can insurance total a car after repairs already started?
Yes. If hidden damage or supplements make repairs uneconomical under the applicable policy and state rules, the claim may shift to total loss.
Does a supplement always mean the car will be totaled?
No. Many supplements are approved as part of normal repairs. A total loss review happens only when the revised numbers justify it.
Who pays for teardown if the car becomes a total loss?
It depends on authorization, policy language, shop charges, claim facts, and state rules. Ask the insurer and shop for an itemized explanation.
Can I disagree with the total loss value?
Yes. Ask for the valuation support, review comparable vehicles and condition details, and follow the dispute process available under the policy and state rules.